October’s National Financial Planning Month is a useful reminder that retirement readiness deserves attention long before an employee’s final day of work. The choices people make today can shape...
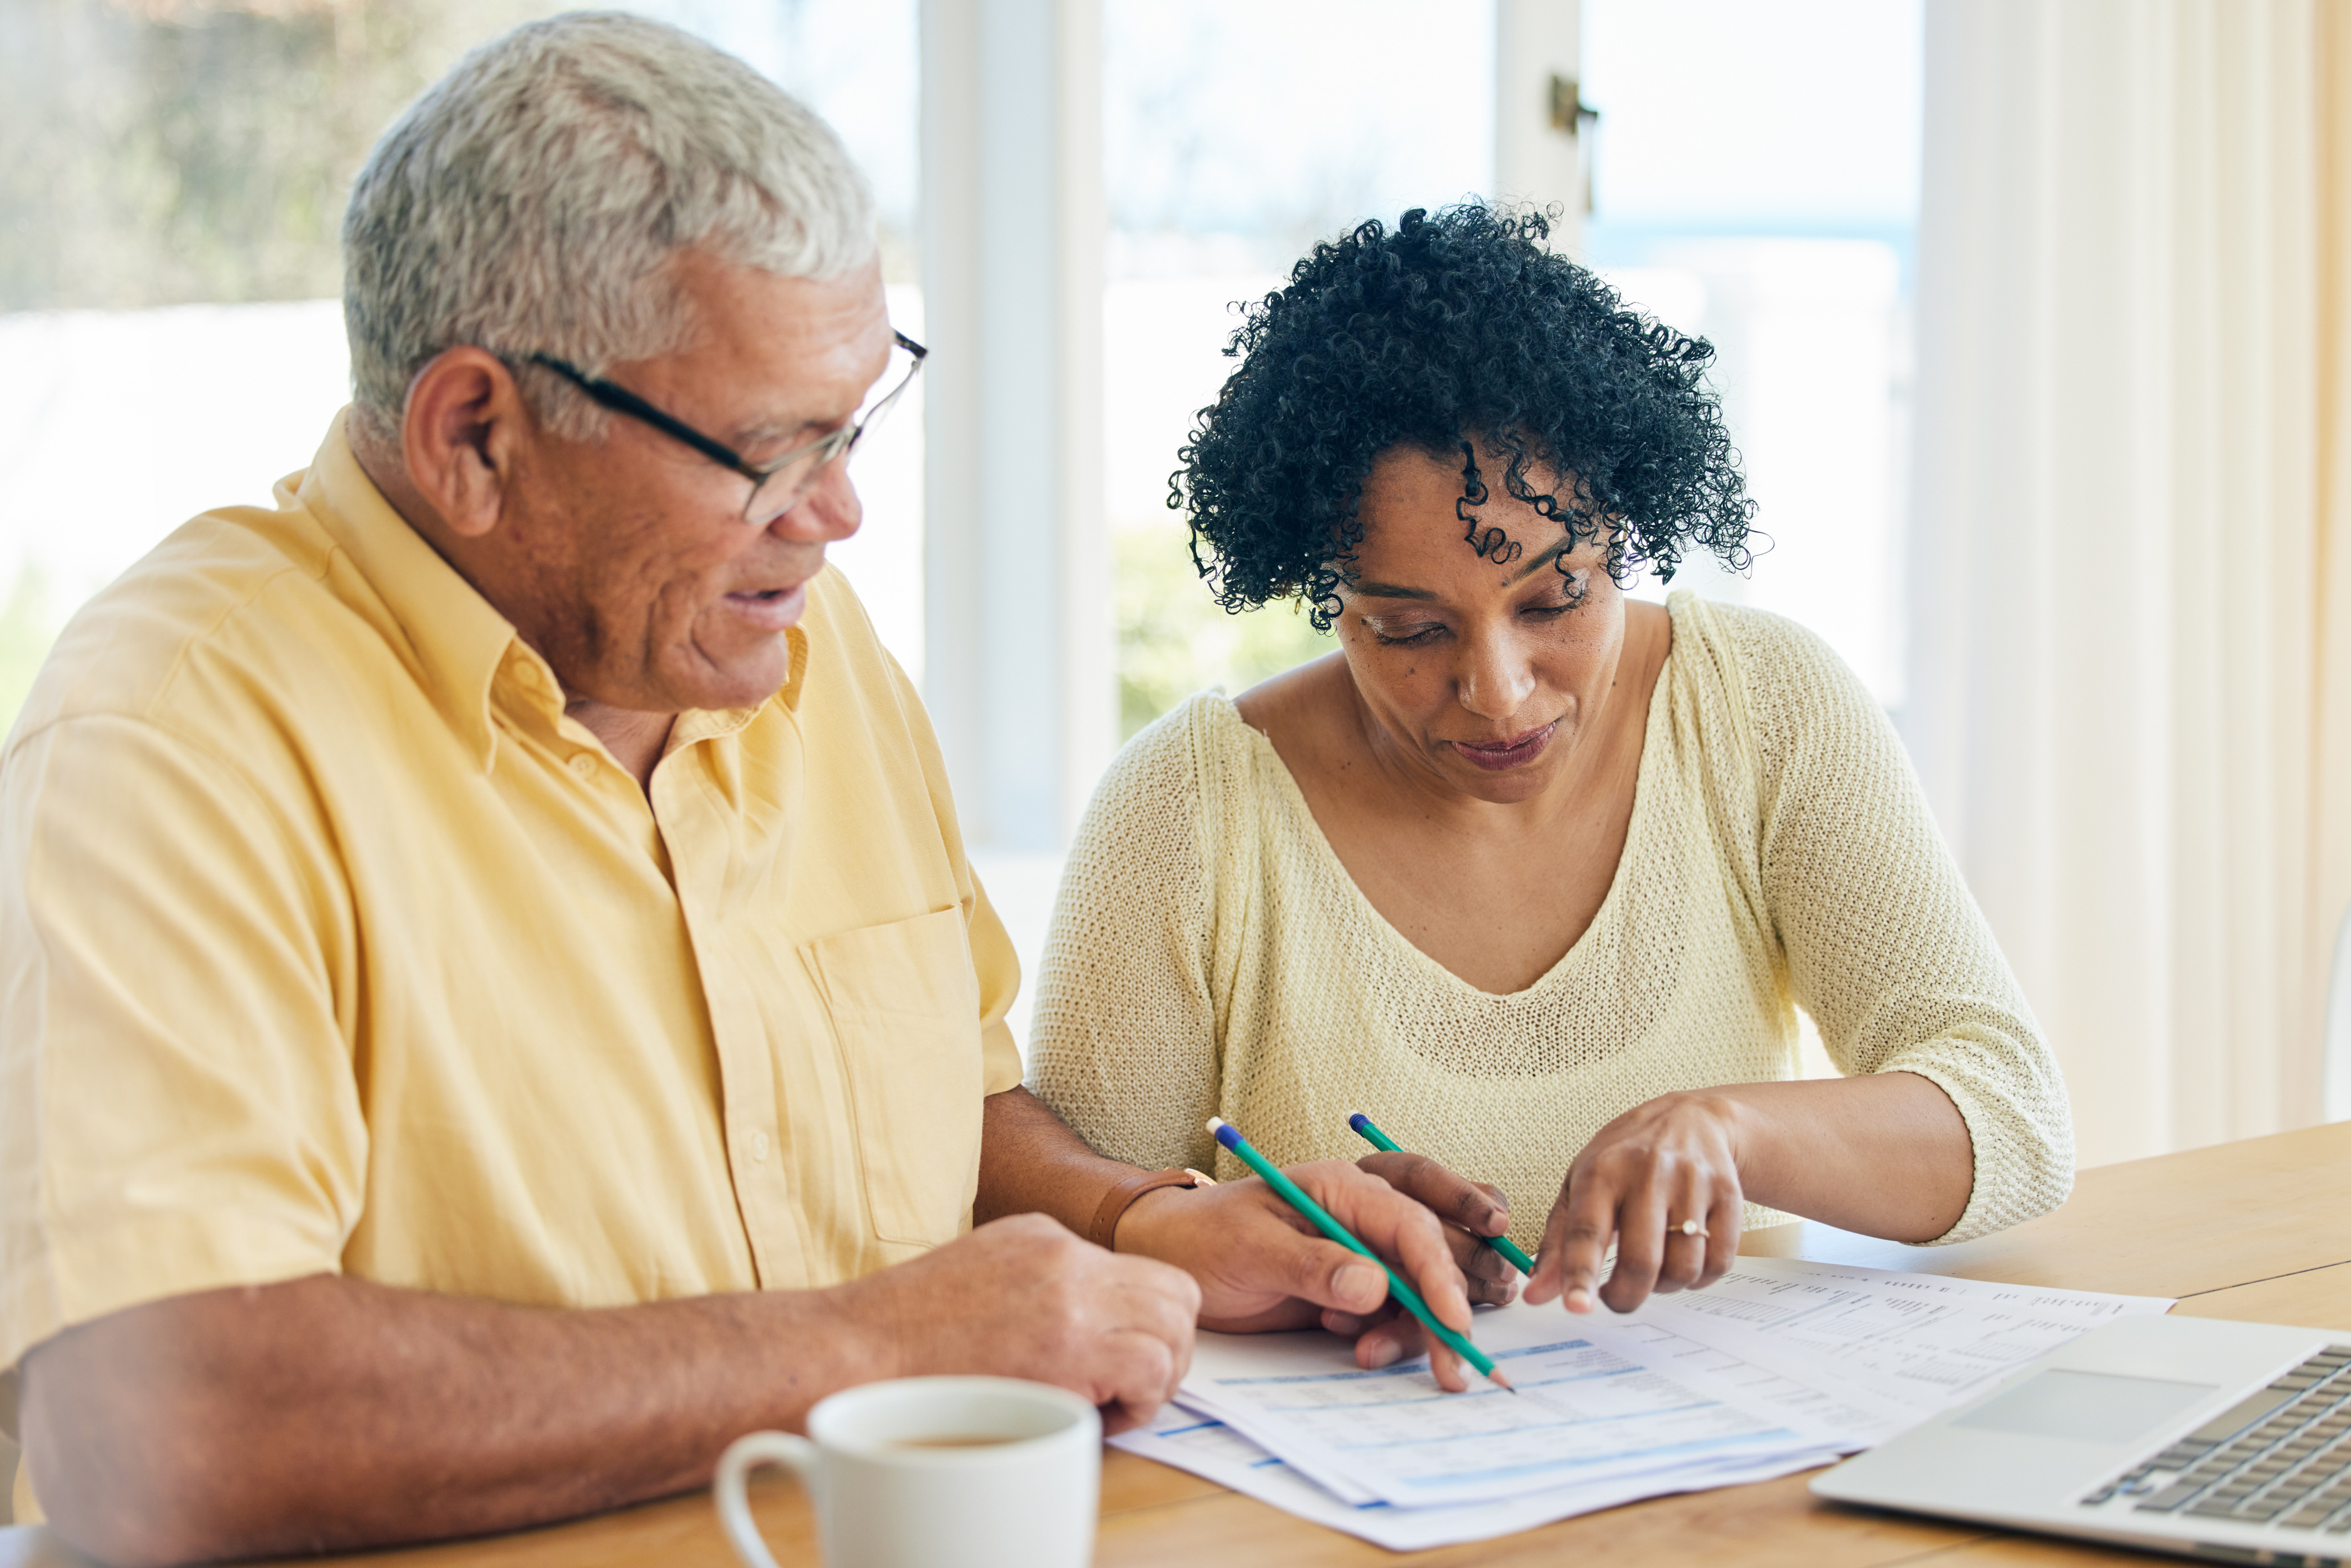
October’s National Financial Planning Month is a useful reminder that retirement readiness deserves attention long before an employee’s final day of work. The choices people make today can shape their long-term financial confidence, which is why employers can play an important role through education, retirement planning resources, and ongoing encouragement.
Retirement readiness is not simply about building a savings balance. It also means understanding available options, evaluating progress, and preparing for the financial realities that may come after a career ends. When employees feel informed about their financial future, they may be better able to focus on their work and make meaningful use of the benefits available to them.
Why Retirement Readiness Matters in the Workplace
Many employees are unsure whether they are making enough progress toward retirement. That uncertainty can create financial stress and make it more difficult to plan with confidence. An employer that makes retirement education part of its benefits strategy shows that it values employees’ well-being beyond their immediate job responsibilities.
Access to retirement planning support can also help employees recognize the value of their workplace benefits. Rather than discussing retirement only during annual enrollment, organizations can keep financial wellness and long-term preparation visible throughout an employee’s career.
For employers, that ongoing attention can help make retirement planning feel less distant and more manageable. For employees, it creates more opportunities to learn, consider their choices, and take informed action over time.
Provide Useful Retirement Planning Resources
Retirement planning often feels more approachable when employees have straightforward tools to use. Practical resources can help them assess their current position and identify reasonable next steps toward their long-term goals.
Employers can support employee financial wellness by making a variety of planning materials available, including:
- Checklists that help employees assess retirement readiness
- Calculators for estimating potential retirement income
- Educational materials that explain key retirement planning concepts
- Financial wellness resources that support thoughtful decision-making
These resources can turn a large, long-range goal into a series of smaller actions employees can understand. When people can see their progress more clearly, they may be more likely to remain involved with their retirement plans and participate consistently.
Education can be especially helpful when it is simple, clear, and easy to revisit. Employees do not need to have every answer at once; they need dependable information that helps them move forward with greater awareness.
Look Beyond the Savings Account Balance
Saving is a central part of retirement planning, but it is only one element of a complete picture. Employees also benefit from considering what retirement could cost and how their spending patterns may change after they leave the workforce.
Resources that address budgeting, expected health care expenses, housing costs, and lifestyle goals can help employees form more realistic expectations. Reviewing anticipated income alongside potential expenses provides a fuller view of retirement than concentrating only on account balances.
Encouraging employees to consider these broader financial questions can make retirement preparation feel more practical. It helps connect today’s decisions to the kind of future they hope to create.
Help Employees Track Their Progress
Retirement planning can seem overwhelming when employees do not know how to tell whether they are on the right path. Clear reference points and understandable milestones can make progress easier to evaluate while providing motivation to stay engaged.
Employers can share guidance on retirement savings milestones, contribution approaches, Social Security considerations, and retirement income planning. These topics can give employees a stronger understanding of where they are today and where there may be opportunities to improve their long-term financial plans.
Regular reviews also encourage employees to make smaller adjustments as circumstances change. Taking action over time can feel more achievable than waiting until retirement is close at hand.
Keep Retirement Education Going Year-Round
Retirement readiness is not accomplished in a single benefits meeting or annual enrollment period. Personal circumstances, financial goals, and economic conditions can all change, making ongoing education an important component of retirement planning.
Organizations can promote greater engagement by sharing financial wellness resources throughout the year. Reminders to review retirement plans annually, information about available planning tools, and opportunities for one-on-one guidance can help keep retirement preparation top of mind.
Educational workshops and similar opportunities can also give employees a welcoming setting to ask questions and build confidence. When retirement education becomes an ongoing conversation, employees have more chances to revisit their plans and make informed decisions as their needs evolve.
How Comprehensive Financial Planning Can Help
For many people, retirement planning is connected to other financial decisions. Tax strategies, estate planning considerations, investment guidance, and future income needs can all influence how someone views retirement readiness.
McLean Advisory Group believes comprehensive financial planning should help clients see how those areas work together. Through its three blind mice approach, the firm brings together financial advisory, tax planning, and legal support to help clients consider the full scope of their financial lives.
For people 55 and older, especially those nearing retirement, this type of client education can offer valuable perspective. A New Jersey financial advisor can help individuals better understand the questions that may affect their own retirement plans, financial priorities, and long-term goals.
Supporting Employees Supports the Whole Organization
Helping employees prepare for retirement can do more than support their personal finances. Employees who feel more confident about their future may be better positioned to engage with workplace benefits and make thoughtful decisions about their long-term goals.
A strong retirement readiness strategy also communicates that an organization cares about the future well-being of its workforce. By providing practical tools, meaningful education, and continuous support, employers can help build financial confidence while improving the employee experience.
National Financial Planning Month is a timely opportunity to make retirement readiness an ongoing priority rather than a one-time initiative. Investing in financial wellness education today can help create a more informed, engaged, and prepared workforce for tomorrow.
McLean Advisory Group provides retirement planning and wealth management guidance for clients in Ocean County, Burlington County, northern Atlantic County, and beyond. Our team is here to help individuals and families explore practical approaches to long-term financial confidence.
Building wealth can change the questions families ask about money. Instead of focusing only on accumulating assets, the conversation often becomes how to enjoy today while protecting flexibility, supporting future goals, and preserving the opportunities wealth can create. For high-asset clients, the issue is often not whether a purchase is affordable now, but whether ongoing spending continues to fit within a broader financial vision.
As income and assets grow, lifestyle choices often grow as well. A larger home, more travel, additional properties, private memberships, and everyday conveniences may become part of life. Enjoying that success matters, but balancing lifestyle spending and long-term wealth preservation calls for thoughtful financial decision-making.
Make Lifestyle Growth a Deliberate Choice
A key part of wealth management is making sure lifestyle expansion is intentional. Spending can naturally rise as financial resources increase, yet each new commitment should still support the goals a family has established. What begins as a discretionary expense can gradually become an expected part of monthly or annual cash flow.
Purposeful spending often provides more value than spending simply because it is possible. Many families find greater satisfaction when their resources reflect what they genuinely care about, whether that involves helping family members, enjoying meaningful travel, pursuing personal interests, or making charitable gifts. Keeping those priorities in view can help lifestyle decisions feel rewarding without losing sight of long-term financial security.
Connect Spending Decisions to Personal Priorities
Comprehensive financial planning is more effective when current spending is connected to a clear understanding of what matters most. Every household has a different vision for its resources, and those priorities can guide both how wealth is used today and how it is preserved for the future.
For some people, travel and experiences take priority. Others may place greater importance on philanthropy, education planning, supporting children or grandchildren, future opportunities, or retirement planning. Identifying the areas that carry the most personal value helps direct financial resources toward the goals that can provide lasting fulfillment.
Separate Liquidity, Lifestyle Needs, and Long-Term Assets
Many high-asset clients benefit from organizing wealth into distinct categories instead of viewing every asset in the same way. This framework can create greater clarity around spending choices, cash flow needs, and investment guidance.
A practical structure may include:
- Accessible funds for emergencies, tax obligations, and unexpected opportunities.
- Assets and cash flow designated for recurring household needs, lifestyle expenses, and experiences.
- Long-term investments intended to support growth, wealth preservation, and estate planning goals.
Dividing resources in this manner can help families see how much capital may be available for current spending while maintaining resources for future priorities. It can also support investment and financial strategies that are designed around different time horizons and purposes.
Update Financial Strategies as Life Changes
Lifestyle expectations do not remain fixed, and the capital needed to support them may increase over time. A spending level that appears manageable today may require substantially more resources in the years ahead when inflation, taxes, health care expenses, and market changes are considered.
That is why savings plans, investment allocations, and tax strategies deserve regular attention. Periodic reviews can help ensure that each part of a financial plan continues to work together as circumstances, goals, and market conditions evolve. Wealth management is not static; it requires flexibility as life changes.
Preserve Flexibility Within the Portfolio
Wealth preservation does not have to mean giving up opportunities for growth. A durable long-term strategy can seek an appropriate balance among growth potential, stability, and access to funds when they are needed.
Portfolio flexibility can become increasingly important as a family takes on more lifestyle commitments. Maintaining sufficient liquidity and cash flow may help cover expenses without forcing changes to long-term investments at an inconvenient time. At the same time, an investment portfolio should be able to adapt as market conditions, tax considerations, and family priorities shift.
Regular reviews with a financial advisory team can help determine whether investments are still aligned with both present needs and future goals. This ongoing process supports a balance between protecting wealth and maintaining the opportunity for continued growth.
Review Recurring Expenses With the Future in Mind
Lifestyle inflation can be one of the less obvious challenges that comes with growing wealth. Over time, occasional purchases may develop into recurring obligations that affect a household’s long-term cash flow.
Second homes, club memberships, household staff, luxury vehicles, and similar commitments can add considerable value to daily life. They can also create expenses that continue year after year. These choices are not necessarily a problem, but their combined effect may reduce flexibility if they are not evaluated in the context of broader financial goals.
Families may benefit from revisiting recurring expenses periodically to confirm that they still reflect current priorities. These conversations can be especially helpful during major life changes, retirement planning discussions, or periods of changing market conditions.
Keep the Larger Wealth Plan in View
For many individuals and families age 55 and older, financial planning extends well beyond personal spending. Providing for future generations, supporting charitable causes, planning for business succession, and addressing estate planning needs can become more important over time.
A well-coordinated wealth management strategy should support the lifestyle you want today while considering the long-term impact you want your wealth to have. When spending, investment guidance, cash flow planning, tax strategies, and legacy objectives work together, families can be better positioned to enjoy their success while preserving future possibilities.
Balancing lifestyle spending with wealth preservation is an ongoing process, not a one-time decision. At McLean Advisory Group, our comprehensive financial planning approach brings financial advisory, tax planning, and legal coordination together through our Three Blind Mice approach. For families in Ocean County, Burlington County, Atlantic County, and beyond, our team can help evaluate how your spending structure, investments, and long-term goals fit within your overall financial plan.
This commentary was prepared by a 3rd party, Levitate, and McLean Advisory group for Scott McLean. It does not necessarily reflect the views of Foundations Investment Advisors, LLC (“Foundations”) and is provided for educational purposes only and the contents are solely maintained by and the responsibility of the applicable 3rd party . The 3rd party content is subject to change at any time without notice, and does not represent an express or implied opinion or endorsement of any specific investment opportunity, investment strategy or planning strategy. Foundations in no way deems reliable any statistical data or information obtained from or prepared by third party sources in this commentary, nor does Foundations guarantee its accuracy or completeness. No legal or tax advice is provided or intended.
This commentary was prepared by a 3rd party, Levitate, and McLean Advisory group for Scott McLean. It does not necessarily reflect the views of Foundations Investment Advisors, LLC (“Foundations”) and is provided for educational purposes only and the contents are solely maintained by and the responsibility of the applicable 3rd party . The 3rd party content is subject to change at any time without notice, and does not represent an express or implied opinion or endorsement of any specific investment opportunity, investment strategy or planning strategy. Foundations in no way deems reliable any statistical data or information obtained from or prepared by third party sources in this commentary, nor does Foundations guarantee its accuracy or completeness. No legal or tax advice is provided or intended.